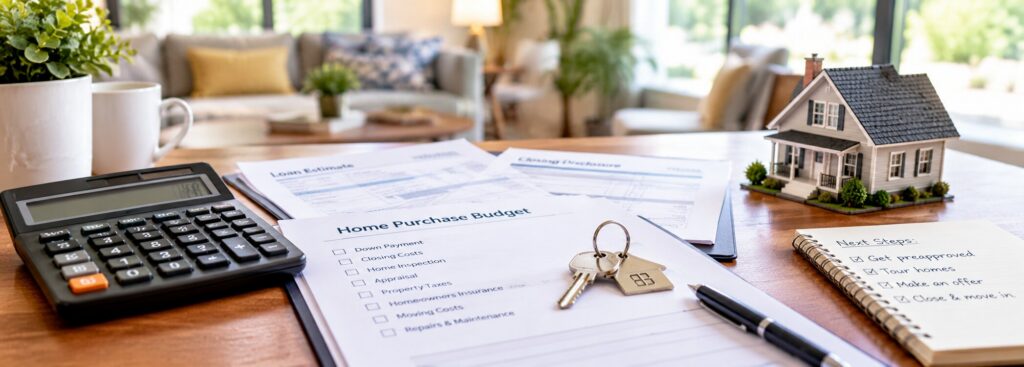
Buying a home in the Inland Empire involves more than saving for a down payment. Buyers also need to plan for closing costs, inspections, insurance, moving expenses, and the ongoing cost of maintaining a property. Understanding these expenses before beginning your search can help you choose a home that fits your budget without putting unnecessary pressure on your finances.
Whether you are considering a home in Riverside, Moreno Valley, Perris, Corona, Jurupa Valley, or San Bernardino, the total cost of buying will depend on the property’s price, your mortgage, local taxes, insurance requirements, and the terms of your purchase agreement.
This guide explains the main expenses to consider when buying a home in the Inland Empire, including costs that first-time buyers sometimes overlook. It also covers practical ways to prepare financially before making an offer.
1. Your Down Payment Is Only the Starting Point
The down payment is the portion of the purchase price you pay upfront rather than borrowing through your mortgage. The amount required depends on your loan program, lender requirements, credit profile, and financial circumstances.
Some conventional mortgage programs allow eligible buyers to put down less than 20%. Certain government-backed loan programs may also offer lower down-payment options to qualified applicants. However, a smaller down payment can result in a larger loan balance and may involve mortgage insurance or other program-specific costs.
For example, a buyer purchasing a $500,000 home with a 5% down payment would contribute $25,000 toward the purchase price. That does not mean the buyer needs only $25,000 in savings. Closing costs, prepaid expenses, moving costs, and money for unexpected repairs may also be necessary.
Before deciding how much to put down, speak with a qualified lender about available loan options and compare the estimated monthly payments. Keeping some savings available after closing can be just as important as reaching a particular down-payment percentage.
2. Closing Costs When Buying a Home in California
Closing costs are expenses associated with completing a real estate transaction and arranging your mortgage. Depending on the property and loan, these may include lender fees, appraisal fees, title services, escrow services, recording fees, and other transaction-related charges.
Buyers may also need to pay certain prepaid expenses at closing, such as initial homeowners insurance premiums, property tax amounts, or mortgage interest. The exact charges vary, so it is important to review a lender’s Loan Estimate and the final Closing Disclosure carefully.
For planning purposes, some buyers set aside approximately 2% to 5% of the purchase price for closing costs, but this is only a broad estimate. Actual costs may fall outside that range depending on the transaction, financing, local fees, and any negotiated seller contributions.
On a $500,000 purchase, a 2% to 5% planning range would equal $10,000 to $25,000. This illustration is not a quote or a prediction of what your transaction will cost. Ask your lender and escrow provider for an estimate based on the property you intend to purchase.
3. Home Inspections and Other Property Evaluations
A home inspection can help you understand the condition of a property before completing your purchase. Although an inspection adds to your upfront expenses, it may identify issues that deserve further investigation or affect your decision to proceed.
Depending on the property, buyers may want to investigate the roof, plumbing, electrical systems, heating and cooling equipment, foundation, drainage, and signs of moisture or pest activity. An inspector may recommend further evaluation by a specialist if a potential concern is identified.
Additional evaluations may be relevant for properties with pools, retaining walls, older systems, unusual construction features, or other conditions that require specialist knowledge. Not every property needs every type of inspection, so discuss appropriate options with your real estate professional and qualified inspectors.
Review available seller disclosures and ask questions about known repairs or property concerns. An inspection does not guarantee that every defect will be found, but it can provide useful information to help you make a more informed decision.
4. Property Taxes and Supplemental Tax Bills
Property taxes are an ongoing cost of homeownership in California. The amount depends on the property’s assessed value, the applicable tax rate, and any voter-approved assessments or other charges that apply to the property.
California’s general property tax rate is commonly described as 1% of assessed value, but the total bill can be higher because local assessments and other charges may apply. Buyers should review the actual tax information for the property rather than assuming that every home in a city has the same effective tax rate.
After a property changes ownership, its assessed value may be reassessed under California rules. A supplemental property tax bill may follow the transfer. This bill is separate from the regular annual tax bill and can catch new homeowners off guard if they have not budgeted for it.
Before closing, ask how property taxes will be handled in the transaction, what amounts are expected to be collected, and whether a supplemental bill may be issued later. You can also review relevant information through the county assessor or tax collector responsible for the property.
5. Homeowners Insurance and Other Coverage
Homeowners insurance can be a significant factor in determining whether a property is affordable. Premiums depend on several factors, including the property’s location, construction, age, coverage limits, deductible, claims history, and the insurance provider’s underwriting rules.
In California, availability and pricing can vary considerably between properties. Some homes may require additional research to obtain suitable coverage, and certain locations may present higher wildfire or other property-related risks. Buyers should investigate insurance availability early rather than waiting until the final stages of escrow.
Your mortgage lender will generally require appropriate property insurance. Depending on the property and loan requirements, additional coverage may also be relevant. Standard homeowners policies do not automatically cover every possible risk, so review exclusions and coverage limits with a qualified insurance professional.
Request quotes for the specific property you are considering. An insurance estimate based on a different home or a broad online calculator may not reflect the actual cost of coverage for your purchase.
6. Mortgage Payments and Other Monthly Housing Costs
Your monthly mortgage payment is only one part of the cost of owning a home. Depending on your loan, the payment may include principal and interest, and your lender may collect property taxes and homeowners insurance through an escrow account.
You should also account for utilities, routine maintenance, repairs, and any applicable homeowners association dues. These costs can vary according to the home’s size, age, location, energy efficiency, and shared amenities.
When comparing properties, calculate the total expected monthly cost rather than focusing exclusively on the mortgage payment. A lower-priced home that needs major repairs or has high insurance costs may not necessarily be less expensive to own than a better-maintained alternative.
Ask your lender for an estimate of the mortgage payment under the proposed loan terms. Then create a separate budget for costs that are not included in that payment, such as utilities, maintenance, and HOA fees.
7. Moving Expenses, Appliances, and Initial Setup
Moving into a home can involve several smaller expenses that add up quickly. Depending on your circumstances, you may need to pay for professional movers, a rental truck, packing materials, storage, utility connections, or time away from work.
You may also need basic household items or appliances. Some homes include major appliances, while others may not. Confirm what is included in the purchase agreement before assuming that items such as a refrigerator, washer, dryer, or other equipment will remain.
Consider making a list of immediate needs and items that can wait. Essential repairs, safety equipment, and necessary appliances should take priority over decorative upgrades or nonessential purchases.
Planning these costs in advance can help you avoid relying on credit cards or using the savings you intended to keep for emergencies.
8. Maintenance and Unexpected Repairs
Every home requires maintenance, even when it appears to be in good condition. Common expenses may include servicing heating and cooling systems, maintaining landscaping, repairing plumbing fixtures, cleaning gutters, or addressing wear and tear.
Older homes may require more attention to major systems, while newer properties can still develop unexpected issues. The condition of the roof, plumbing, electrical systems, appliances, and exterior materials can help you estimate which expenses may arise sooner.
There is no single maintenance budget that works for every home. Consider the property’s age and condition, review inspection findings, and ask qualified contractors for estimates when significant work may be required.
It is sensible to maintain an emergency reserve after closing. If buying a home uses every dollar of your available savings, even a modest repair could become financially stressful.
9. HOA Fees and Community Assessments
Some homes and condominium communities have homeowners association fees. These fees may support shared landscaping, common areas, amenities, exterior maintenance, or other services defined by the association’s governing documents.
HOA fees differ by community and may change over time. Some associations may also levy special assessments to pay for significant shared expenses. Buyers should not assume that a monthly fee will remain unchanged or that every repair is covered by the association.
Before purchasing a property with an HOA, review the applicable documents, current fees, rules, reserve information, and any disclosed special assessments. Ask questions about restrictions that could affect your plans, including pet rules, parking, exterior changes, or use of shared facilities.
These details are particularly important if you are comparing a condominium or planned community with a detached home that has no HOA fees.
10. Ways to Prepare Your Home Buying Budget
Preparing a complete budget before house hunting can make the buying process easier. Start by estimating the down payment and obtaining a lender’s estimate of closing costs. Then add property-specific expenses such as insurance, inspections, moving costs, and likely initial repairs.
Use these steps to organize your finances:
- Ask for written estimates. Request a Loan Estimate from your lender and confirm expected transaction costs with the appropriate professionals.
- Compare insurance options early. Obtain quotes for the specific property before you become committed to an unrealistic monthly budget.
- Review property taxes. Check applicable county information and ask about potential supplemental tax bills.
- Budget for inspections and repairs. Allow for appropriate inspections and investigate major concerns before finalizing your decision.
- Keep emergency savings. Avoid allocating every available dollar to the purchase if you can reasonably preserve a reserve.
- Investigate assistance programs. Ask qualified lenders or program administrators about current first-time buyer assistance and eligibility requirements.
Buyers should also compare mortgage offers and understand how interest rates, loan terms, down payments, and mortgage insurance affect the total cost over time.
Frequently Asked Questions About Home Buying Costs
How much money should I save beyond the down payment?
The amount depends on the purchase price, loan program, closing costs, inspections, insurance, moving expenses, and property condition. Request transaction-specific estimates and preserve savings for unexpected costs when possible.
Are closing costs included in the mortgage?
Closing costs are commonly paid at closing, although some loan structures and negotiated arrangements may allow certain costs to be financed or covered by seller contributions when permitted. Ask your lender to explain which options are available for your transaction.
Can a seller help pay my closing costs?
Seller contributions may be negotiable, subject to the purchase agreement, loan-program limits, and applicable rules. They are not guaranteed. Discuss the available options with your real estate professional and lender before making assumptions about your cash needed to close.
What costs are often overlooked by first-time buyers?
Commonly overlooked expenses include supplemental property taxes, insurance premiums, moving costs, utility setup, HOA assessments, maintenance, and initial repairs or appliances. Reviewing these items before making an offer can help you plan more realistically.
Plan Your Inland Empire Home Purchase With Confidence
Buying a home in the Inland Empire can be an important milestone, but a sound plan should account for more than the purchase price. Understanding closing costs, insurance, property taxes, maintenance, and moving expenses can help you choose a home that fits your finances both now and after closing.
Glorimar “Glori” Cole, The Pet-Friendly REALTOR®, helps buyers navigate the home buying process with clear communication and practical guidance. Whether you are exploring Riverside, Moreno Valley, Perris, Corona, Jurupa Valley, or another Inland Empire community, taking time to prepare your budget can help you move forward with greater confidence.
Explore home buying resources or contact Glori Cole to discuss your home buying plans.
Costs and loan requirements vary by property, lender, and buyer circumstances. Examples in this article are illustrative only and are not a loan quote, tax estimate, insurance quote, or guarantee of eligibility for financial assistance. Confirm current figures with qualified professionals before making a purchase decision.